Financial KPIs Every Business Owner Must Track
Running a successful business requires more than increasing sales. Business owners must understand how much profit they generate, how efficiently they use their resources, whether customers pay on time, and whether they have enough cash to meet upcoming expenses.
Many businesses generate substantial revenue but struggle with cash flow. Others have healthy sales but declining profit margins. Some businesses continue expanding without realising that their outstanding customer payments and operating costs are increasing faster than their income.
These problems often occur because business owners do not monitor the right financial indicators consistently.
This is where financial Key Performance Indicators (KPIs) become essential.
Financial KPIs help business owners measure performance, identify risks, evaluate profitability and make informed decisions. By tracking the right indicators every month, businesses can understand their financial position and take corrective action before small issues become serious problems.
In this guide, we explain the financial KPIs every business owner must track, including their formulas, practical examples and how to use them to improve business performance.
What Are Financial KPIs?
Financial Key Performance Indicators are measurable values that help businesses evaluate their financial performance against specific objectives.
They convert accounting data into information that management can use to make decisions.
For example, a Profit and Loss statement may show that a company generated ₹50 lakh in revenue. However, revenue alone does not reveal whether the business is profitable, whether it collects payments quickly or whether its debt is manageable.
Financial KPIs provide additional insight into these questions.
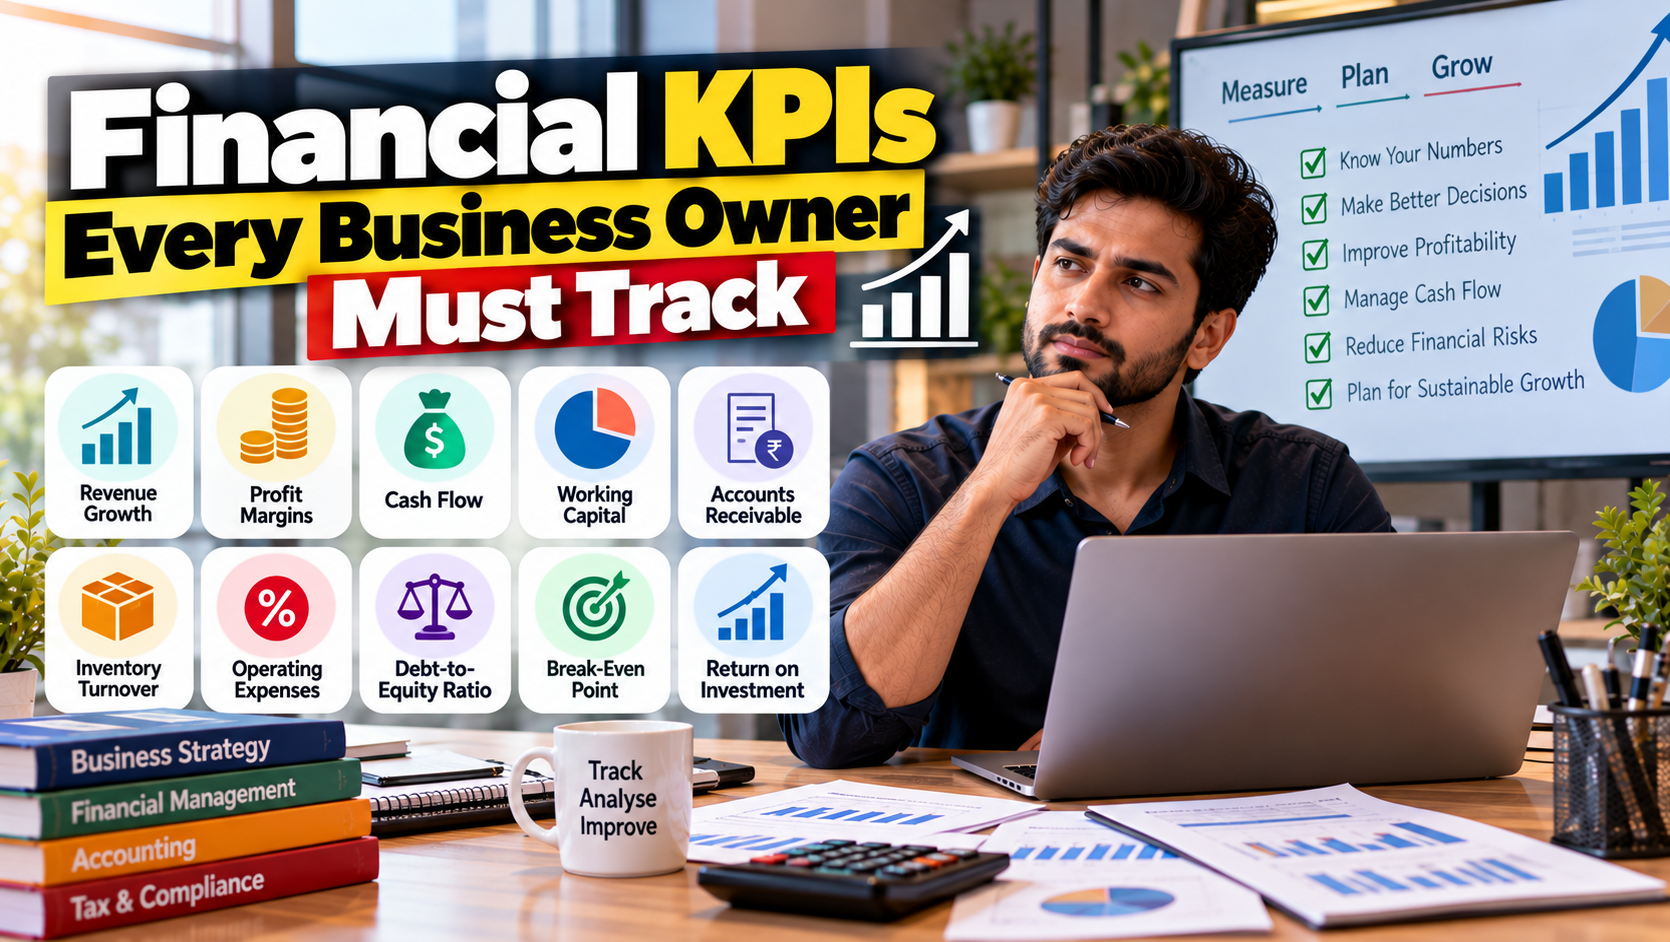
Common financial KPIs include:
-
Revenue growth rate
-
Gross profit margin
-
Net profit margin
-
Operating expenses ratio
-
Operating cash flow
-
Working capital
-
Accounts receivable days
-
Inventory turnover
-
Current ratio
-
Debt-to-equity ratio
-
Return on investment
-
Break-even point
Not every business needs to track every metric. The most useful KPIs depend on the company's industry, business model, size and financial objectives.
15 Financial KPIs Every Business Owner Should Track
1. Revenue Growth Rate
Revenue growth measures how quickly a business's sales are increasing or decreasing over a specific period.
It helps owners understand whether their business is expanding, stagnating or losing sales momentum.
Formula
[
\text{Revenue Growth (%)}=
\frac{\text{Current Revenue}-\text{Previous Revenue}}
{\text{Previous Revenue}}\times100
]
Example
Suppose a company generated ₹10 lakh in revenue last month and ₹12 lakh this month.
Revenue growth is:
[
\frac{12-10}{10}\times100=20%
]
The company has achieved 20% revenue growth compared with the previous month.
Why it matters
Tracking revenue growth helps businesses:
-
Measure sales performance
-
Identify seasonal patterns
-
Evaluate marketing effectiveness
-
Set realistic targets
-
Plan future investments
However, revenue growth should never be evaluated alone. If sales increase while expenses rise even faster, the business may become less profitable.
Business tip: Compare revenue growth with profit growth and cash flow to understand whether the business is growing sustainably.
2. Gross Profit Margin
Gross profit margin shows how much revenue remains after accounting for the direct cost of goods sold or the relevant direct costs of delivering a service.
It is particularly useful for product businesses, manufacturers, wholesalers and retailers.
Formula
[
\text{Gross Profit Margin (%)}=
\frac{\text{Revenue}-\text{Cost of Goods Sold}}
{\text{Revenue}}\times100
]
Example
A retailer generates ₹10 lakh in sales and has a cost of goods sold of ₹6 lakh.
Gross profit is:
₹10,00,000 − ₹6,00,000 = ₹4,00,000
Gross profit margin:
[
\frac{4}{10}\times100=40%
]
The business retains ₹4 lakh after covering the cost of goods sold, before other operating expenses.
Why it matters
A declining gross margin may indicate:
-
Increasing purchase costs
-
Excessive discounting
-
Higher production costs
-
Pricing problems
-
Product mix changes
-
Inventory wastage
Business tip: Monitor gross profit margin by product or service category where practical. Overall profitability can hide products that consistently generate weak margins.
3. Net Profit Margin
Net profit margin measures the proportion of revenue that remains as profit after the expenses included in the chosen net profit measure.
It gives owners a broader view of business profitability than gross profit margin.
Formula
[
\text{Net Profit Margin (%)}=
\frac{\text{Net Profit}}{\text{Revenue}}\times100
]
Example
Suppose a business generates ₹20 lakh in revenue and records ₹2 lakh in net profit for the period.
[
\frac{2}{20}\times100=10%
]
The business earns ₹10 in net profit for every ₹100 of revenue.
For meaningful comparisons, make sure the net profit measure is defined consistently, particularly when comparing results before or after tax.
Why it matters
Net profit margin helps business owners assess:
-
Overall cost efficiency
-
Pricing performance
-
Financial sustainability
-
Profitability trends
-
The impact of overhead expenses
Business tip: Track net profit margin monthly and compare it with the same period in previous years when seasonality affects sales.
4. Operating Expense Ratio
The operating expense ratio measures operating expenses relative to revenue.
It helps business owners understand how much of their income is consumed by the day-to-day costs of running the business.
Formula
[
\text{Operating Expense Ratio (%)}=
\frac{\text{Operating Expenses}}{\text{Revenue}}\times100
]
The exact expenses included should be defined consistently. Interest and income tax are generally analysed separately from operating expenses.
Example
A company generates ₹15 lakh in revenue and incurs ₹3 lakh in operating expenses.
[
\frac{3}{15}\times100=20%
]
Operating expenses represent 20% of revenue.
Why it matters
Monitoring this KPI can reveal:
-
Rising payroll costs
-
Excessive administrative spending
-
Inefficient marketing expenditure
-
Increasing rent and utilities
-
Overhead growth that exceeds sales growth
A lower ratio is not automatically better in every situation. Some businesses need to invest in staff, technology or marketing to support future growth.
Business tip: Review major expense categories separately rather than cutting costs indiscriminately.
5. Operating Cash Flow
Operating cash flow measures the cash generated or consumed by a business's normal operating activities over a period.
It helps answer an important question: Is the core business generating enough cash to support its operations?
A business can report accounting profits while experiencing cash shortages because customers have not paid their invoices or because inventory and other working capital requirements have increased.
What to monitor
-
Monthly operating cash flow
-
Cash collected from customers
-
Cash paid to suppliers
-
Payroll and operating payments
-
Changes in receivables and inventory
-
Recurring cash deficits
Example
A business receives ₹8 lakh from customers during a month and pays ₹6.5 lakh for operating activities.
If these are the relevant operating cash inflows and outflows, the simplified net cash generated is ₹1.5 lakh.
A complete operating cash flow calculation may include other operating items and adjustments.
Why it matters
Positive operating cash flow can support routine expenses, debt servicing and business development. Repeated negative operating cash flow may indicate that the business needs to review collections, costs, pricing or working capital.
Business tip: Monitor cash flow alongside profit. Neither metric alone provides the complete picture.
6. Working Capital
Working capital measures the difference between current assets and current liabilities.
It provides a basic view of the resources available to support short-term business operations.
Formula
[
\text{Working Capital}=
\text{Current Assets}-\text{Current Liabilities}
]
Example
A business has:
-
Current assets: ₹12 lakh
-
Current liabilities: ₹8 lakh
Working capital is:
₹12 lakh − ₹8 lakh = ₹4 lakh
The company has positive working capital of ₹4 lakh.
Why it matters
Working capital helps owners assess whether the business has sufficient short-term resources to support its obligations.
Low or negative working capital may indicate pressure, although the implications depend on the business model. Businesses with rapid cash collection and supplier credit can operate differently from companies that hold large amounts of inventory.
Business tip: Review working capital alongside receivable days, inventory turnover and payment terms. The amount alone does not explain how efficiently it is managed.
7. Current Ratio
The current ratio compares current assets with current liabilities.
It is a liquidity indicator that helps assess the company's ability to cover short-term obligations using its current assets.
Formula
[
\text{Current Ratio}=
\frac{\text{Current Assets}}{\text{Current Liabilities}}
]
Example
A company has ₹15 lakh in current assets and ₹10 lakh in current liabilities.
[
\frac{15}{10}=1.5
]
The current ratio is 1.5.
This means the company has ₹1.50 in current assets for every ₹1 of current liabilities.
Why it matters
The ratio can help identify potential liquidity concerns and support discussions with lenders and management.
However, a high current ratio does not always mean the business is financially healthy. Current assets may include slow-moving inventory or overdue receivables that cannot be converted into cash quickly.
Business tip: Review the current ratio together with the quality of receivables, inventory and expected cash inflows.
8. Accounts Receivable Days
Accounts receivable days estimate how long a business takes, on average, to collect money from customers after making credit sales.
Long collection periods can put pressure on working capital and increase the risk of bad debts.
Formula
A common approximation is:
[
\text{Receivable Days}=
\frac{\text{Average Accounts Receivable}}
{\text{Credit Sales}}\times\text{Days in Period}
]
Use credit sales and an appropriate period consistently. A year-end receivable balance can be used as an approximation when average balances are unavailable, but it may be less representative.
Example
Suppose average accounts receivable is ₹3 lakh and annual credit sales are ₹36 lakh.
[
\frac{3}{36}\times365\approx30.4
]
The business takes approximately 30 days to collect its credit sales.
Why it matters
Increasing receivable days may indicate:
-
Late-paying customers
-
Weak credit policies
-
Delayed invoicing
-
Ineffective collection follow-up
-
Disputes over invoices
Business tip: Review an ageing report regularly and investigate invoices that remain unpaid beyond the agreed credit period.
9. Accounts Payable Days
Accounts payable days estimate how long a business takes to pay its suppliers.
Managing supplier payments effectively can help preserve working capital without damaging supplier relationships.
Formula
[
\text{Payable Days}=
\frac{\text{Average Accounts Payable}}
{\text{Credit Purchases}}\times\text{Days in Period}
]
Use credit purchases for the same period where available. Cost of goods sold is sometimes used as a proxy, but the calculation should be labelled accordingly because the two measures are not necessarily identical.
Example
Suppose average accounts payable is ₹2 lakh and annual credit purchases are ₹24 lakh.
[
\frac{2}{24}\times365\approx30.4
]
The business takes approximately 30 days to pay suppliers.
Why it matters
This KPI can help management understand payment patterns and negotiate appropriate supplier terms.
Paying too early may unnecessarily reduce available cash, while paying too late can damage relationships, trigger charges or interrupt supply.
Business tip: Align supplier payment schedules with expected customer collections wherever practical, while meeting contractual obligations.
10. Inventory Turnover Ratio
Inventory turnover measures how frequently a business sells and replaces its inventory during a period.
It is especially useful for retailers, wholesalers and manufacturers.
Formula
[
\text{Inventory Turnover}=
\frac{\text{Cost of Goods Sold}}
{\text{Average Inventory}}
]
Example
A retailer has annual cost of goods sold of ₹48 lakh and average inventory of ₹8 lakh.
[
\frac{48}{8}=6
]
The retailer's inventory turns over six times during the year.
Why it matters
A low turnover ratio may indicate:
-
Slow-moving products
-
Overstocking
-
Weak demand forecasting
-
Excessive purchasing
-
Obsolete inventory
A very high turnover ratio may also require investigation if it results in frequent stockouts or insufficient inventory.
Business tip: Analyse turnover by product category and compare it with sales forecasts, stock availability and supplier lead times.
11. Debt-to-Equity Ratio
The debt-to-equity ratio compares a company's debt with its equity.
It helps owners and lenders understand how the business is financed and how much it relies on borrowing.
Formula
[
\text{Debt-to-Equity Ratio}=
\frac{\text{Debt}}{\text{Equity}}
]
The calculation should specify which debt and equity components are included, particularly when comparing companies.
Example
A business has ₹20 lakh in debt and ₹40 lakh in equity.
[
\frac{20}{40}=0.5
]
The debt-to-equity ratio is 0.5.
This indicates ₹0.50 of debt for every ₹1 of equity under the defined calculation.
Why it matters
A rising ratio can indicate increased financial leverage and potentially greater exposure to interest costs and repayment obligations.
However, acceptable leverage varies significantly by industry, business maturity, asset structure and the stability of cash flows.
Business tip: Review debt-to-equity alongside interest coverage, debt maturity schedules and projected cash flow.
12. Interest Coverage Ratio
The interest coverage ratio measures how comfortably a business's operating earnings cover its interest expense.
It is particularly important for companies that rely on loans to fund operations or expansion.
Formula
[
\text{Interest Coverage Ratio}=
\frac{\text{EBIT}}{\text{Interest Expense}}
]
EBIT means earnings before interest and tax.
Example
Suppose a company has EBIT of ₹6 lakh and interest expense of ₹2 lakh.
[
\frac{6}{2}=3
]
The interest coverage ratio is 3.
The company's EBIT is three times its interest expense for the period.
Why it matters
A declining ratio may indicate that earnings are weakening relative to borrowing costs.
This can become a concern when the company needs additional finance or faces loan repayments during a period of reduced profitability.
Business tip: Monitor the ratio over time and assess whether projected earnings can support the company's debt obligations under less favourable conditions.
13. Break-Even Point
The break-even point is the level of sales at which total revenue equals total costs under the assumptions used in the calculation.
At break-even, the business neither makes a profit nor incurs a loss from the activities included in the model.
Formula
[
\text{Break-Even Sales}=
\frac{\text{Fixed Costs}}
{\text{Contribution Margin Ratio}}
]
The contribution margin ratio is:
[
\frac{\text{Revenue}-\text{Variable Costs}}
{\text{Revenue}}
]
Example
A business has monthly fixed costs of ₹3 lakh and a contribution margin ratio of 30%.
[
\frac{₹3,00,000}{0.30}=₹10,00,000
]
The business needs approximately ₹10 lakh in monthly sales to break even under these assumptions.
Why it matters
Break-even analysis helps business owners:
-
Set sales targets
-
Evaluate pricing
-
Assess new products
-
Plan expansion
-
Understand fixed-cost exposure
-
Estimate the impact of cost changes
The calculation becomes more complex when a business sells multiple products with different contribution margins or when costs change at different activity levels.
Business tip: Recalculate break-even sales when rent, salaries, supplier prices or selling prices change significantly.
14. Return on Investment (ROI)
Return on Investment measures the return generated relative to the investment made.
It can be used to assess marketing campaigns, equipment purchases, new branches, technology projects and other business initiatives.
Formula
[
\text{ROI (%)}=
\frac{\text{Net Return from Investment}}
{\text{Investment Cost}}\times100
]
The method used to calculate net return should be clearly defined and consistent with the investment being assessed.
Example
A business invests ₹2 lakh in a project and earns a net return of ₹50,000 over the period being evaluated.
[
\frac{₹50,000}{₹2,00,000}\times100=25%
]
The ROI is 25% for that measurement period.
Why it matters
ROI helps management compare investment opportunities and evaluate whether resources are being used effectively.
However, ROI alone does not account for every factor. The time taken to generate the return, risk, cash flow and long-term benefits may also matter.
Business tip: When evaluating marketing, distinguish revenue attributed to a campaign from the profit actually generated by it.
15. Budget Variance
Budget variance measures the difference between actual financial performance and the budgeted amount.
It helps business owners determine whether revenue, expenses and other financial results are moving according to plan.
Formula
[
\text{Variance}=
\text{Actual Amount}-\text{Budgeted Amount}
]
The interpretation depends on the metric. Higher-than-budgeted revenue is generally favourable, while higher-than-budgeted expenses are generally unfavourable.
Example
A company budgets ₹2 lakh for monthly marketing expenses but spends ₹2.4 lakh.
Variance:
₹2.4 lakh − ₹2 lakh = ₹40,000 unfavourable expense variance.
Management should investigate whether the additional spending was planned, generated acceptable results or resulted from poor cost control.
Why it matters
Budget variance analysis helps businesses:
-
Control costs
-
Monitor departmental performance
-
Identify unexpected spending
-
Update financial forecasts
-
Improve accountability
-
Adjust plans when business conditions change
Business tip: Do not automatically treat every variance as a problem. Investigate its cause, financial impact and whether it requires corrective action.
How to Choose the Right Financial KPIs for Your Business
Although all 15 KPIs can be useful, tracking too many metrics can make reporting unnecessarily complicated.
Start with the indicators most closely connected to your business objectives and risks.
| Business type | Priority KPIs |
|---|---|
| Retail business | Gross margin, inventory turnover, cash flow, receivable days |
| Manufacturing business | Gross margin, inventory turnover, operating expenses, working capital |
| Service business | Revenue growth, gross margin, operating expenses, receivable days |
| E-commerce business | Gross margin, returns, marketplace fees, cash flow, receivables and settlement reconciliation |
| Startup | Cash runway, revenue growth, burn rate, gross margin and budget variance |
| Professional services firm | Revenue per employee, utilisation where relevant, operating margin and receivable days |
| Loan-funded business | Operating cash flow, debt-to-equity, interest coverage and repayment capacity |
The table is a starting point. The exact KPIs should reflect the company's revenue model, cost structure and management priorities.
Financial KPIs vs Financial Statements
Financial KPIs and financial statements serve different purposes.
Financial statements provide a structured record of financial performance and position. KPIs highlight selected measures that help management monitor particular objectives or risks.
For example:
-
The Profit and Loss statement provides revenue and expense information.
-
The Balance Sheet provides information about assets, liabilities and equity.
-
The cash flow statement explains cash movements.
-
Financial KPIs convert selected information into indicators such as margins, liquidity ratios and turnover measures.
A business should use KPIs alongside its underlying accounting records rather than treating them as a replacement for financial statements.
How Often Should Business Owners Review Financial KPIs?
The ideal review frequency depends on transaction volume, financial risk and the pace of business operations.
Weekly
Useful for monitoring:
-
Cash position
-
Customer collections
-
Major payments due
-
Short-term cash forecasts
-
Unusual transactions
Monthly
Useful for reviewing:
-
Revenue growth
-
Gross and net profit margins
-
Operating expenses
-
Working capital
-
Receivables and payables
-
Budget variance
-
Monthly financial statements
Quarterly
Useful for reviewing:
-
Debt structure
-
Return on investment
-
Strategic financial targets
-
Major cost trends
-
Investment and expansion plans
-
Forecast revisions
High-volume businesses or companies with tight liquidity may need more frequent monitoring. A small business with predictable transactions may be able to review some indicators less frequently.
The important principle is consistency: use the same definitions, review the results regularly and investigate significant changes.
Building a Financial KPI Dashboard
A financial KPI dashboard brings the most important indicators into one report.
Instead of reviewing multiple spreadsheets, management can monitor selected metrics and compare current results with previous periods or planned targets.
A practical dashboard may include:
| KPI | Current period | Previous period | Target | Status |
|---|---|---|---|---|
| Revenue growth | Actual % | Previous % | Planned % | Review trend |
| Gross profit margin | Actual % | Previous % | Target % | Review trend |
| Net profit margin | Actual % | Previous % | Target % | Review trend |
| Operating cash flow | Actual ₹ | Previous ₹ | Planned ₹ | Review cash position |
| Receivable days | Actual days | Previous days | Target days | Review collections |
| Current ratio | Actual ratio | Previous ratio | Internal target | Review liquidity |
| Budget variance | Actual difference | Previous difference | Within approved limits | Investigate exceptions |
These are dashboard fields rather than example performance results. Actual values and targets should come from the company's accounting records and business plan.
A useful dashboard should:
-
Use accurate, reconciled data.
-
Define every KPI clearly.
-
Compare actual performance with targets.
-
Highlight material changes.
-
Show trends over time.
-
Identify who is responsible for follow-up.
-
Link unusual results to an action plan.
A dashboard is useful only when management understands the numbers and acts on the information.
Common Mistakes When Tracking Financial KPIs
1. Focusing Only on Revenue
Sales growth does not guarantee profitability or positive cash flow.
2. Using Incorrect Accounting Data
KPIs calculated from incomplete or unreconciled accounts can create misleading conclusions.
3. Comparing Different Periods Without Context
Seasonality, one-off expenses and changes in business activity can affect comparisons.
4. Using the Same Targets for Every Industry
A healthy margin or liquidity ratio for one business may be unsuitable for another.
5. Tracking Too Many Metrics
A dashboard crowded with indicators can make it harder to identify the most important issues.
6. Ignoring the Reasons Behind Changes
A KPI indicates what may be happening; further analysis is often needed to understand why.
7. Not Taking Corrective Action
Regular reporting has limited value if management does not respond to significant financial risks.
How Professional Accounting Services Help Businesses Track KPIs
Reliable KPIs depend on accurate bookkeeping, regular reconciliation and meaningful financial reporting.
Professional accounting support can help businesses:
-
Maintain up-to-date accounting records
-
Reconcile bank and ledger balances
-
Prepare monthly financial statements
-
Monitor profitability and expenses
-
Track receivables and payables
-
Review GST and tax records
-
Prepare budgets and forecasts
-
Build management reports
-
Identify unusual financial movements
For growing businesses, a Virtual CFO or financial planning professional may also help interpret KPI trends, evaluate investment decisions and develop a financial strategy.
The appropriate level of support depends on the company's size, complexity and internal capabilities.
At Clockwell International LLP, businesses can explore accounting, taxation, compliance and financial reporting support based on their requirements.
Frequently Asked Questions
1. What are the most important financial KPIs for a small business?
A useful starting set includes revenue growth, gross profit margin, net profit margin, operating cash flow, working capital, receivable days and budget variance. The final selection should reflect the business model and key risks.
2. How many financial KPIs should a business track?
There is no universal number. Many businesses benefit from a small set of core KPIs, supported by additional metrics for specific departments or risks.
3. What is the difference between a financial KPI and a financial metric?
A financial metric is a measurable financial value. A KPI is a metric selected because it is especially important for evaluating progress towards a business objective.
4. Can a profitable business still have cash flow problems?
Yes. A business may record revenue and profit but still lack cash because customers have not paid, inventory has increased or significant payments are due.
5. What is a good net profit margin?
There is no single ideal net profit margin for every business. Appropriate margins vary by industry, business model, operating costs, pricing and growth stage. Compare performance with relevant industry information and the company's own historical results.
6. How can financial KPIs improve business decisions?
They help management identify trends, evaluate performance, detect risks and assess the financial impact of operational decisions.
7. Should financial KPIs be reviewed monthly?
Monthly review is a useful baseline for many businesses, but cash flow and other high-risk indicators may require weekly or even daily monitoring.
8. Can accounting software track financial KPIs automatically?
Many accounting and business intelligence systems can calculate and display selected KPIs. However, the accuracy of the results depends on correct data, suitable KPI definitions and appropriate system configuration.
Financial KPIs are essential tools for understanding the real condition of a business.
Revenue growth shows whether sales are increasing. Profit margins reveal how efficiently the company converts sales into profit. Cash flow and working capital indicate whether the business can meet its obligations. Receivable days and inventory turnover help management understand how effectively resources are being managed.
Debt ratios, break-even analysis, ROI and budget variance provide additional insight into financial risk and future decisions.
The most effective approach is to select relevant KPIs, calculate them consistently, compare them with appropriate targets and investigate significant changes.
Remember: tracking financial KPIs is not just about measuring past performance. It is about using financial information to make better decisions for the future.
Whether you operate a startup, retail shop, manufacturing company, service business or growing SME, a reliable financial reporting process can help you identify problems earlier and plan with greater confidence.
Start with a small set of meaningful KPIs, review them regularly and expand your dashboard as your business becomes more complex.
Disclaimer: This article is intended for general educational purposes and does not constitute accounting, tax, investment or financial advice. KPI definitions and appropriate targets vary by business and industry. Consult a qualified professional when making decisions specific to your company.
Published on October 14, 2026