1. What Is Accounting Outsourcing?
Accounting outsourcing means hiring an external professional or accounting firm to handle some or all of a company's accounting and finance-related activities.
Instead of maintaining a complete accounting department internally, a business can outsource tasks such as:
-
Bookkeeping
-
Sales and purchase accounting
-
Bank reconciliation
-
GST accounting
-
GST return preparation
-
TDS compliance
-
Payroll accounting
-
Accounts payable
-
Accounts receivable
-
Financial reporting
-
Tax-related accounting support
-
Management reports
-
Year-end accounts preparation
The level of outsourcing can vary.
A small business might outsource only bookkeeping and GST compliance, while a growing company may outsource almost its entire accounting function.
2. Why Are Businesses Outsourcing Accounting?
The main reason is simple:
Businesses want professional accounting without the cost and complexity of building a large internal accounting team.
However, cost is only one factor.
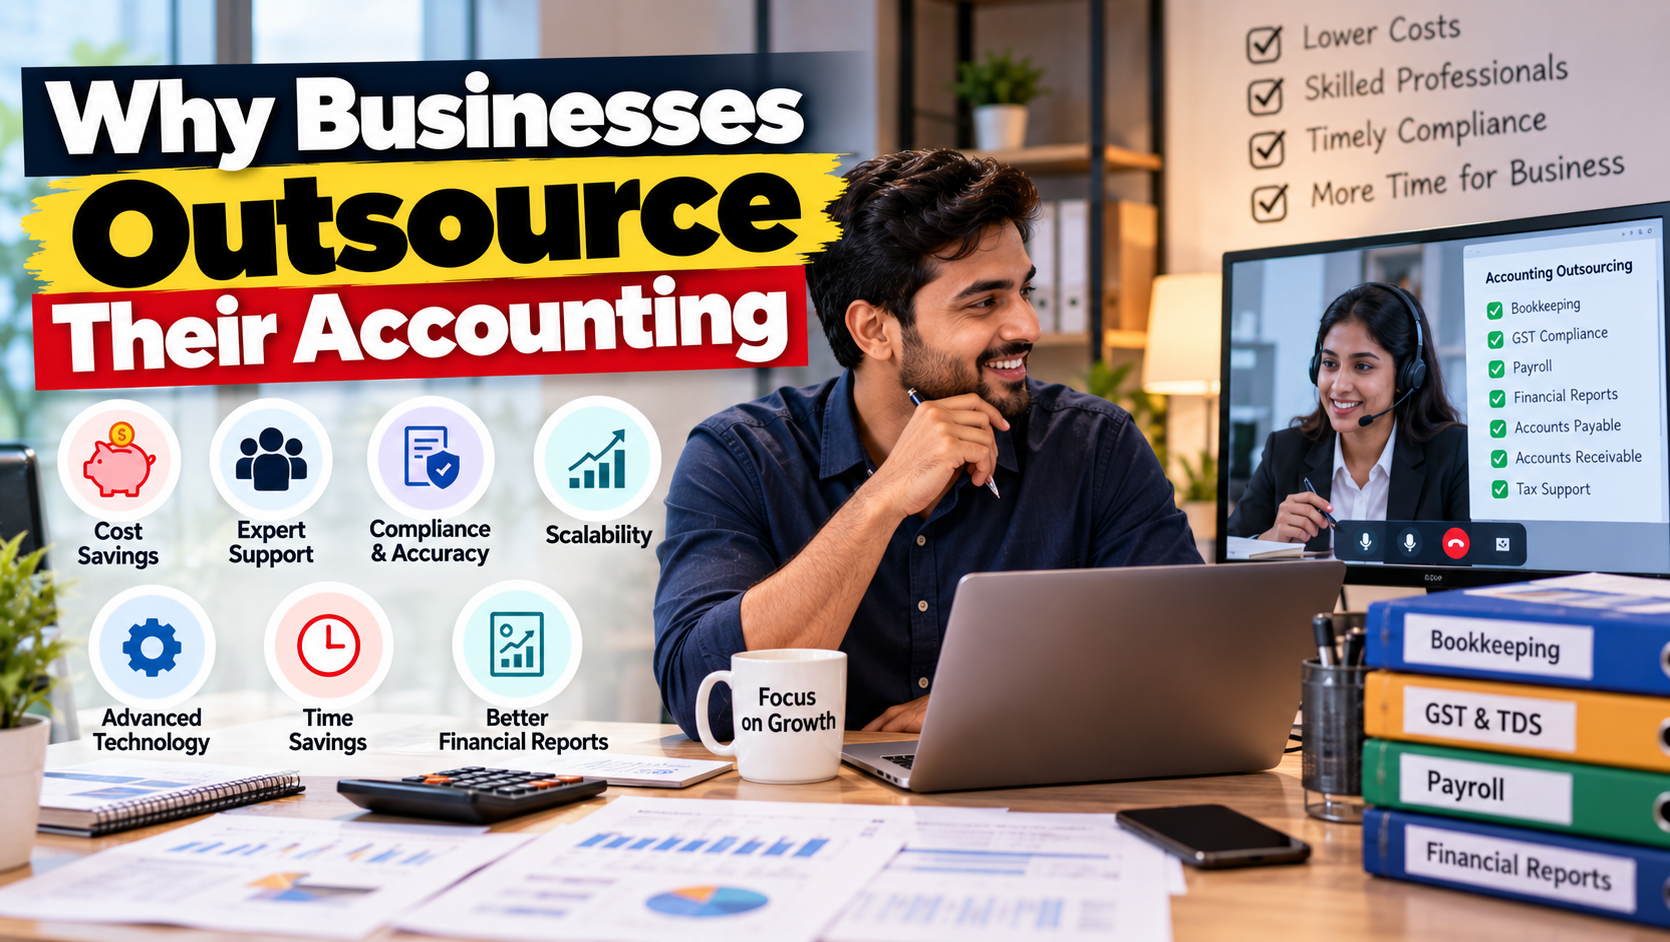
Businesses also outsource accounting to gain:
-
Access to experienced professionals
-
Better compliance management
-
Faster financial reporting
-
Improved bookkeeping accuracy
-
Accounting technology
-
Business continuity
-
Scalability
-
Better financial visibility
-
Reduced administrative workload
For business owners, this can mean more time to focus on sales, customers, operations and growth.
3. Accounting Is More Than Data Entry
One common misconception is that accounting simply means entering invoices into software.
Modern accounting involves much more.
A business may need to manage:
Transactions → Bookkeeping → Reconciliation → GST → TDS → Payroll → Financial Statements → Tax Planning → Business Decisions
If these processes are poorly managed, the business may not know its actual financial position.
For example, a company could have strong sales but poor cash flow because customers are paying late.
Without proper accounting reports, the owner may not identify the problem quickly.
Professional accounting can turn transaction data into useful financial information.
4. Cost Savings
One of the biggest reasons companies outsource accounting is cost efficiency.
Maintaining an internal accounting department can involve:
-
Accountant salaries
-
Senior accountant or finance manager salaries
-
Employee benefits
-
Recruitment costs
-
Training
-
Accounting software
-
Hardware
-
Office space
-
Employee replacement costs
-
Compliance training
Outsourcing converts many of these fixed costs into a more predictable service expense.
Example
Suppose a small company needs:
-
One accountant
-
One senior finance employee
-
Accounting software
-
Training and other employee-related costs
The total annual cost can become significant.
Instead, the company may outsource bookkeeping, GST, payroll and financial reporting to an accounting service provider for a fixed monthly fee.
The exact savings depend on the business and scope of work, but outsourcing can be particularly attractive for small and medium-sized businesses.
5. Access to Accounting Experts
Hiring one accountant does not necessarily provide expertise in every area of finance and taxation.
A professional accounting firm may have access to people with experience in:
-
Bookkeeping
-
GST
-
Income tax
-
TDS
-
Payroll
-
Audit
-
Financial reporting
-
Corporate compliance
-
Management accounting
This creates a major advantage.
Instead of depending entirely on one employee, the business gets access to a broader team.
6. Better GST ComplianceGST compliance can become complicated as a business grows.
Businesses may need to manage:
-
GST invoices
-
Input Tax Credit
-
GSTR-1
-
GSTR-3B
-
E-invoicing where applicable
-
E-way bills
-
Credit notes
-
Debit notes
-
Sales reconciliation
-
Purchase reconciliation
-
GST notices
Errors can lead to:
-
Incorrect tax payments
-
ITC discrepancies
-
Interest
-
Penalties
-
Notices
-
Cash-flow problems
Outsourcing accounting can provide a dedicated process for tracking GST-related transactions and compliance.
However, businesses should always ensure that the outsourced provider has appropriate expertise and that the business retains oversight of its tax obligations.
7. Accurate Bookkeeping
Accurate bookkeeping is the foundation of financial management.
Poor bookkeeping can result in:
-
Incorrect profit calculations
-
Missing expenses
-
Duplicate entries
-
Unreconciled bank balances
-
Incorrect receivables
-
Incorrect payables
-
GST discrepancies
-
Poor management decisions
An outsourced accounting team can establish regular bookkeeping procedures and reconciliation processes.
This is particularly useful for businesses where the owner does not have accounting expertise.
8. Bank Reconciliation
Bank reconciliation compares accounting records with actual bank transactions.
For example:
Accounting records: ₹12,50,000
Bank statement: ₹12,32,500
A reconciliation process identifies why the difference exists.
Possible reasons include:
-
Bank charges
-
Unpresented cheques
-
Direct deposits
-
Payment gateway settlements
-
Interest
-
Duplicate entries
-
Unrecorded transactions
Regular reconciliation helps businesses maintain more reliable financial records.
9. Better Financial Reporting
Business owners need more than a list of transactions.
They need to understand:
-
Revenue
-
Gross profit
-
Net profit
-
Operating expenses
-
Cash flow
-
Receivables
-
Payables
-
Inventory
-
Tax liabilities
-
Business performance
An outsourced accounting team can prepare periodic reports such as:
Profit & Loss Statement
Shows business revenue, expenses and profitability.
Balance Sheet
Shows assets, liabilities and equity.
Cash Flow Report
Shows how cash moves through the business.
Receivables Report
Shows how much customers owe the company.
Payables Report
Shows how much the company owes suppliers.
These reports help management make better decisions.
10. Business Owners Save Time
For many entrepreneurs, accounting is a major administrative burden.
A business owner may spend hours every week:
-
Collecting invoices
-
Checking payments
-
Following up with customers
-
Recording expenses
-
Reviewing bank statements
-
Preparing GST data
-
Communicating with accountants
Outsourcing can reduce the amount of time the owner spends on routine accounting activities.
That time can instead be used for:
-
Sales
-
Marketing
-
Customer relationships
-
Product development
-
Hiring
-
Business expansion
-
Strategic planning
11. Reduced Dependence on One Employee
This is an often-overlooked advantage.
Suppose a company has only one accountant.
If that employee:
-
Resigns
-
Goes on extended leave
-
Becomes unavailable
-
Moves to another company
the business may suddenly struggle to maintain accounting operations.
Outsourcing provides access to a team rather than one individual.
This can improve continuity.
12. Access to Better Accounting Technology
Professional accounting firms often use accounting software and digital workflows to manage client accounts.
Depending on the provider, businesses may benefit from:
-
Cloud accounting
-
Automated bank feeds
-
Digital invoice processing
-
Expense management
-
Payroll systems
-
GST reconciliation tools
-
Document management
-
Financial dashboards
-
Automated reminders
-
Digital approvals
Small businesses may find it expensive or unnecessary to build these systems internally.
Outsourcing can provide access to technology as part of the service.
13. Scalability
A business's accounting requirements change as it grows.
A company with ₹20 lakh in annual revenue may have relatively simple accounting.
A company with ₹10 crore in revenue may have:
-
Multiple bank accounts
-
Hundreds of customers
-
Multiple vendors
-
Payroll
-
Inventory
-
Branches
-
Inter-State transactions
-
GST reconciliation
-
Larger compliance requirements
An internal accounting setup may need to expand significantly.
An outsourced accounting provider can often increase the level of service as the business grows.
14. Outsourcing Is Not Only for Small Businesses
Accounting outsourcing is often associated with startups and small businesses.
But larger businesses also outsource accounting functions.
A medium-sized company might outsource:
-
Payroll
-
Accounts payable
-
Accounts receivable
-
Bookkeeping
-
Tax compliance
-
Financial reporting
while keeping strategic finance functions internally.
This creates a hybrid finance model.
15. Bookkeeping vs Outsourced Accounting
These terms are sometimes used interchangeably, but they are not exactly the same.
Bookkeeping
Usually focuses on recording transactions.
Examples:
-
Sales entries
-
Purchase entries
-
Expense entries
-
Bank entries
-
Ledger maintenance
Outsourced Accounting
Can cover a broader range of activities:
-
Bookkeeping
-
Reconciliation
-
GST
-
TDS
-
Payroll
-
Financial statements
-
Management reports
-
Accounts receivable
-
Accounts payable
-
Financial analysis
Therefore, businesses should clarify the exact scope before hiring an accounting service provider.
16. What Accounting Functions Can Be Outsourced?
Almost every routine accounting function can potentially be outsourced.
Bookkeeping
-
Sales
-
Purchases
-
Expenses
-
Journal entries
-
Ledger management
Tax Compliance
-
GST
-
TDS
-
Income tax support
-
Tax reconciliations
Accounts Receivable
-
Customer invoices
-
Payment tracking
-
Outstanding reports
-
Receivable ageing
Accounts Payable
-
Vendor invoices
-
Payment schedules
-
Outstanding reports
Payroll
-
Salary calculations
-
Payroll records
-
Statutory deductions
-
Payroll reports
Financial Reporting
-
Profit & Loss
-
Balance Sheet
-
Cash flow
-
Management reports
17. Better Accounts Receivable Management
Late customer payments can seriously affect cash flow.
An outsourced finance team can maintain:
-
Customer ageing reports
-
Outstanding invoices
-
Payment schedules
-
Collection follow-ups
-
Receivable dashboards
For example:
| Customer | Outstanding | Days |
|---|---|---|
| Customer A | ₹1,50,000 | 15 |
| Customer B | ₹85,000 | 45 |
| Customer C | ₹2,10,000 | 90+ |
The business can immediately identify which customers require attention.
18. Better Accounts Payable Management
The same principle applies to suppliers.
An accounting team can track:
-
Vendor invoices
-
Due dates
-
Outstanding balances
-
Payment schedules
-
Vendor reconciliations
This can help prevent:
-
Late-payment issues
-
Duplicate payments
-
Missed invoices
-
Supplier disputes
It also helps management plan cash requirements.
19. Improved Cash Flow Visibility
Profit does not always mean cash.
A business can show a profit on its Profit & Loss statement and still experience a cash shortage.
For example:
Sales: ₹50 lakh
Profit: ₹8 lakh
But if customers have not paid ₹20 lakh yet, the business may still face a cash-flow problem.
Proper accounting helps management understand:
-
How much cash is available
-
How much customers owe
-
What payments are due
-
What taxes are payable
-
What expenses are coming
This makes cash-flow planning easier.
20. Outsourced Accounting and Virtual CFO Services
As a business grows, it may need more than bookkeeping.
This is where Virtual CFO services can become useful.
A Virtual CFO may support:
-
Budgeting
-
Financial forecasting
-
Cash-flow planning
-
Business performance analysis
-
Cost control
-
Investment decisions
-
Management reporting
-
Financial strategy
The progression can look like:
Bookkeeping → Accounting → Financial Reporting → Management Accounting → Virtual CFO
This allows businesses to add financial expertise as they grow.
21. Better Internal Controls
Accounting outsourcing can also help businesses establish financial controls.
Examples include:
-
Approval workflows
-
Expense authorization
-
Payment controls
-
Bank reconciliation
-
Vendor verification
-
Invoice matching
-
Segregation of duties
-
Monthly closing procedures
Strong internal controls reduce the risk of financial errors and unauthorized transactions.
However, outsourcing itself does not automatically guarantee strong controls. The business must define access rights, approval procedures and responsibilities clearly.
22. Data Security and Confidentiality
Accounting records contain sensitive information.
They may include:
-
Bank information
-
Customer information
-
Vendor details
-
Salaries
-
Tax information
-
Financial statements
-
Business performance data
Therefore, businesses should carefully evaluate an accounting provider's security practices.
Before outsourcing, ask about:
-
Data access controls
-
Password security
-
Two-factor authentication
-
Cloud storage
-
Backup procedures
-
Employee access
-
Confidentiality agreements
-
Data retention
-
Data transfer procedures
A professional accounting relationship should include clear confidentiality and data-security expectations.
23. Is Outsourcing Accounting Cheaper?
In many cases, outsourcing can be more cost-effective than maintaining a complete internal team.
But the answer depends on:
-
Business size
-
Transaction volume
-
Number of employees
-
Number of GST registrations
-
Number of branches
-
Complexity of accounting
-
Required reporting
-
Industry
-
Service provider pricing
A business should compare total cost, not just salary.
In-house accounting cost
Salary + benefits + recruitment + training + software + infrastructure + management time
Outsourced accounting cost
Professional service fee + applicable software/data costs
The correct comparison is between the total cost and the quality of service received.
24. When Should a Business Outsource Accounting?
There is no universal revenue threshold.
However, outsourcing becomes worth considering when:
1. The owner is spending too much time on accounting
2. Accounting errors are increasing
3. GST and tax compliance are becoming difficult
4. The business has multiple employees
5. Transactions have increased significantly
6. Customers are delaying payments
7. Management does not receive timely financial reports
8. The accountant is overloaded
9. The business is expanding into multiple States
10. The company needs financial expertise without hiring a large team
25. When Should You Keep Accounting In-House?
Outsourcing is not always the best solution.
An internal finance team may be preferable when:
-
The company is very large
-
Finance is strategically critical
-
There are highly complex internal processes
-
Large-scale financial planning is required
-
The business needs finance professionals physically involved in daily operations
Many companies eventually adopt a hybrid model.
For example:
Internal Finance Manager + Outsourced Bookkeeping + External Tax Professionals
This can combine internal control with external expertise.
26. How to Choose an Accounting Outsourcing Company
Choosing the right provider is critical.
Do not select a service provider only because they offer the lowest price.
Evaluate:
Experience
Do they understand your industry?
Qualifications
Does the team have appropriate accounting and tax expertise?
Technology
Do they use reliable accounting and document-management systems?
Communication
How quickly do they respond?
Reporting
What reports will you receive?
Compliance
How will GST, TDS and other obligations be tracked?
Security
How is financial data protected?
Scalability
Can they handle your business as it grows?
27. Questions to Ask Before Outsourcing
Before signing an agreement, ask:
-
What accounting tasks are included?
-
What is excluded?
-
How frequently will books be updated?
-
Who will manage GST compliance?
-
Who will handle reconciliation?
-
Will monthly financial reports be provided?
-
What software will be used?
-
How will documents be shared?
-
Who has access to financial data?
-
What happens if the assigned accountant is unavailable?
-
How are errors handled?
-
What is the turnaround time?
-
Are there additional charges?
-
Can the service scale with business growth?
These questions can prevent misunderstandings later.
28. Common Mistakes When Outsourcing Accounting
Choosing the Cheapest Provider
Low cost does not necessarily mean good value.
Giving Unlimited Access
Employees or vendors should receive only the access they need.
Not Defining Responsibilities
The business should clearly know who is responsible for each task.
Ignoring Monthly Review
Business owners should still review financial reports regularly.
Not Reconciling Accounts
Outsourcing does not eliminate the need for reconciliation.
No Written Agreement
The scope, confidentiality and responsibilities should be documented.
Expecting the Accountant to Run the Business
An accounting provider can provide financial information and support, but management remains responsible for business decisions.
29. How the Outsourcing Process Usually Works
A professional outsourcing workflow can look like this:
Step 1: Initial Assessment
The accounting provider reviews the business structure and current accounting system.
Step 2: Data Collection
Existing accounting records, invoices, bank statements and tax information are collected.
Step 3: Accounting System Setup
The provider configures the accounting software and chart of accounts.
Step 4: Opening Balance Verification
Opening balances are checked and reconciled.
Step 5: Daily/Weekly Bookkeeping
Transactions are recorded regularly.
Step 6: Reconciliation
Bank, customer and supplier accounts are reconciled.
Step 7: Compliance
GST, TDS and other applicable compliance activities are prepared.
Step 8: Monthly Closing
The accounts are reviewed and finalized.
Step 9: Management Reporting
Financial reports are provided to management.
Step 10: Review and Improvement
The process is continuously improved as the business grows.
30. What Does a Good Outsourced Accounting System Look Like?
A strong outsourced accounting system should provide:
Source Documents
↓
Transaction Recording
↓
Bank Reconciliation
↓
GST/TDS Reconciliation
↓
Monthly Closing
↓
Financial Statements
↓
Management Reporting
↓
Business Decisions
The objective is not simply to "maintain accounts."
The objective is to create reliable financial information for better business decisions.
31. Outsourcing Accounting for Startups
Startups usually want to control expenses.
Hiring a full finance team may not be practical during the early stages.
Outsourcing allows startups to access accounting support while maintaining a lean structure.
A startup may outsource:
-
Bookkeeping
-
GST
-
TDS
-
Payroll
-
Tax compliance
-
Financial statements
As the startup grows, it can gradually build an internal finance function.
32. Outsourcing Accounting for SMEs
Small and medium-sized enterprises often benefit significantly from accounting outsourcing.
An SME may not need a full-time CFO, but it may still need:
-
Accurate books
-
GST compliance
-
Monthly reports
-
Cash-flow monitoring
-
Receivable management
-
Tax planning support
Outsourcing can provide these capabilities without building a large finance department.
33. Outsourcing Accounting for E-commerce Businesses
E-commerce businesses have unique accounting requirements.
They may operate through:
-
Amazon
-
Flipkart
-
Shopify
-
Meesho
-
Payment gateways
-
Their own website
Accounting becomes complicated because of:
-
Marketplace commissions
-
Returns
-
Refunds
-
TCS
-
Shipping charges
-
Payment gateway fees
-
Discounts
-
Multiple settlement reports
A specialized accounting provider can reconcile these transactions and provide more reliable financial records.
34. Outsourcing Accounting for Multiple Branches
Businesses with multiple branches can face additional accounting challenges.
Each branch may have:
-
Sales
-
Purchases
-
Expenses
-
Employees
-
Inventory
-
Cash collections
Centralized outsourced accounting can consolidate branch-level information into management reports.
For example:
| Branch | Revenue | Expenses | Profit |
|---|---|---|---|
| Branch A | ₹18L | ₹12L | ₹6L |
| Branch B | ₹14L | ₹11L | ₹3L |
| Branch C | ₹22L | ₹15L | ₹7L |
Management can quickly identify which branches are performing better.
35. Does Outsourcing Mean Losing Control?
No.
A well-designed outsourcing arrangement should actually improve financial control.
The business owner should retain control over:
-
Bank accounts
-
Payment approvals
-
Financial decisions
-
Budgets
-
Accounting access
-
Major transactions
The outsourced team handles the accounting process while management retains decision-making authority.
36. How Often Should Outsourced Accounts Be Reviewed?
The ideal frequency depends on the business.
Small business
Monthly review may be sufficient.
Growing SME
Weekly monitoring and monthly financial closing can be useful.
High-volume business
Daily or weekly dashboards may be appropriate.
The important principle is:
Do not wait until the end of the financial year to understand your business finances.
Monthly accounting creates much better visibility.
37. Key Benefits of Outsourcing Accounting
The major advantages can be summarized as:
Cost Efficiency
Reduce the cost of maintaining a large internal finance team.
Professional Expertise
Access experienced accounting and tax professionals.
Better Compliance
Improve GST, TDS and other compliance processes.
Accurate Records
Maintain reliable books and reconciliations.
Better Reporting
Receive timely financial information.
Time Savings
Allow business owners to focus on growth.
Scalability
Increase accounting support as the business expands.
Technology
Access modern accounting and reporting systems.
Continuity
Reduce dependence on one internal employee.
Better Decisions
Use financial information to make informed decisions.
38. Accounting Outsourcing Checklist
Before outsourcing, check:
-
Define accounting requirements
-
Identify monthly transaction volume
-
List all GST registrations
-
Identify payroll requirements
-
List tax compliance requirements
-
Review existing accounting records
-
Select accounting software
-
Define responsibilities
-
Define reporting frequency
-
Establish document-sharing process
-
Set access permissions
-
Sign confidentiality agreement
-
Agree on service fees
-
Establish monthly review process
39. Final Thoughts
Accounting is not just a compliance requirement.
It is the financial information system of a business.
When accounting records are accurate and updated, business owners can understand:
-
Where money is coming from
-
Where money is going
-
Which customers owe money
-
Which suppliers need to be paid
-
How profitable the business is
-
How much tax may be payable
-
Which products or branches perform better
-
Whether the company can afford expansion
For many small and growing businesses, building a large internal finance department is unnecessary.
Outsourced accounting can provide access to professional expertise, technology and structured financial processes at a more flexible cost.
However, outsourcing should not mean giving up financial control.
The best model is one where the business owner maintains decision-making authority while an experienced accounting team manages the day-to-day financial processes and provides timely information.
Ultimately, the question should not be:
"Should I outsource accounting because it is cheaper?"
Instead, ask:
"Can outsourcing give my business better accounting, better compliance and better financial visibility than my current system?"
If the answer is yes, accounting outsourcing may be a valuable strategic decision for your business.
Frequently Asked Questions
What is accounting outsourcing?
Accounting outsourcing means hiring an external accounting professional or firm to manage some or all of a company's accounting and finance functions.
Is accounting outsourcing suitable for small businesses?
Yes. Small businesses can outsource bookkeeping, GST, payroll, tax compliance and financial reporting without maintaining a large internal accounting department.
Is outsourced accounting cheaper than hiring an accountant?
It can be, depending on the company's transaction volume, complexity and required services. Businesses should compare total employment and infrastructure costs with the outsourcing fee.
Can GST filing be outsourced?
Yes. Businesses can engage professional accounting or tax service providers to assist with GST accounting, reconciliation and return compliance.
Can payroll be outsourced?
Yes. Payroll processing and related accounting and statutory calculations can be outsourced.
Will I lose control over my accounts if I outsource?
Not necessarily. Access controls, approval procedures and reporting responsibilities can be designed so that management retains control over financial decisions.
Is outsourcing accounting suitable for startups?
Yes. Startups can outsource routine finance functions and expand their accounting capabilities as the business grows.
What is the difference between bookkeeping and accounting outsourcing?
Bookkeeping mainly involves recording financial transactions. Outsourced accounting can include bookkeeping plus reconciliation, compliance, reporting, payroll, accounts receivable, accounts payable and other finance functions.
When should a business outsource accounting?
Consider outsourcing when accounting becomes time-consuming, compliance becomes complicated, transaction volume increases, financial reports are delayed, or the business needs professional expertise without building a large internal team.
Published on October 7, 2026